America's ten largest cities hold tens of millions of square feet of vacant industrial space—from Chicago's 4.5% vacancy to Austin's 19.4%—while data center developers face multi-year grid queues and power-constrained greenfield pipelines. The jurisdictions that act first to streamline conversion of these properties will capture a disproportionate share of the industry's capital—and a new stream of property, sales, utility, and payroll tax revenue that expands the tax base without raising rates on existing residents. This is a competitive race: the gap between a 90-day adaptive-reuse approval and a multi-year greenfield process can determine which city wins a billion-dollar facility.
I. Existing Infrastructure
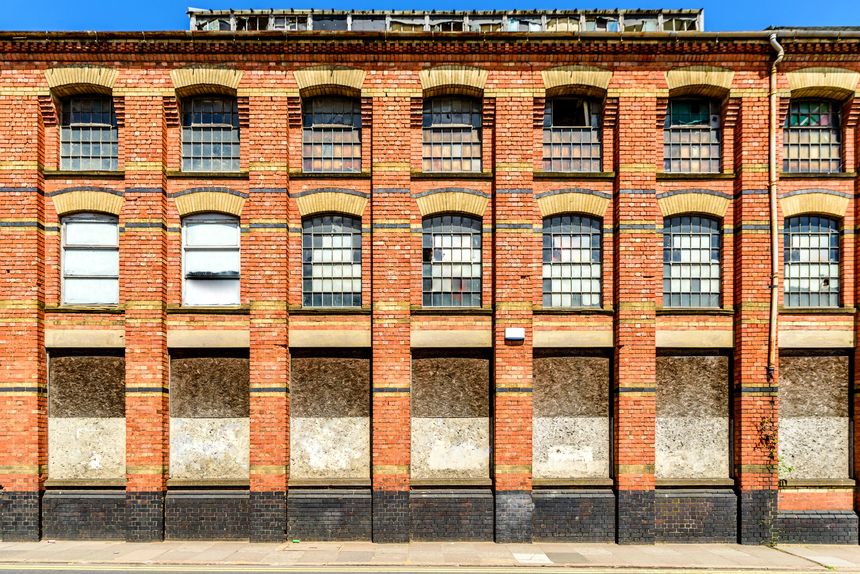
Vacant industrial buildings feature heavy floor loads, reinforced structures, clear heights exceeding 30 feet, and proximity to fiber trunk lines—attributes that align directly with data center requirements. Consulting experts and the EPA identify industrial conversions as the fastest path to operational capacity, noting that existing utility corridors and switchgear can be modernized rather than built from scratch. For example, Patmos Hosting converted a 400,000-square-foot abandoned Kansas City printing facility into an AI training center in 90 days—versus the industry-standard two-year greenfield timeline. In New York (7.0–7.8% vacancy), Chicago (4.5%), and Philadelphia (10.3%), vacant parcels sit on established fiber routes enabling low-latency deployments that suburban campuses cannot match.
II. Power Supply
Access to power is the defining bottleneck. Cities with elevated vacancy often retain legacy electrical allocations from prior manufacturing tenants. Austin (19.4%), Philadelphia (10.3–11.0%), and San Antonio (10.3%) each have decommissioned capacity that could, with substation upgrades, serve 25–100+ MW facilities. In PJM territory—covering Philadelphia and Chicago (via ComEd)—capacity auction prices surged 800% for 2025/2026, underscoring the value of existing interconnection points. Houston, on the independent ERCOT grid, benefits from Texas's deregulated market and lower electricity costs. Constraints remain: legacy feeders require transformer upgrades, and developers will need to co-invest in substation modernization or bring behind-the-meter generation.
III. Water Access
Hyperscale data centers consume 3–5 million gallons of water daily for cooling. Chicago (Lake Michigan), Houston (Galveston Bay), Philadelphia (Delaware and Schuylkill Rivers), and New York (Hudson and East Rivers) hold natural advantages over water-scarce markets like Phoenix and San Antonio, where community opposition over water-table depletion is mounting. Successful projects will require negotiated water-use agreements, recycling investments, and water-usage-effectiveness reporting.
IV. Tax Revenue
The fiscal calculus is shifting. Virginia's data center sales tax exemption cost $1.94 billion in FY 2025; Georgia projects $2.5 billion in FY 2026; Ohio's cost $1.6 billion in 2025—twelve times its original estimate. As states curtail these subsidies, data centers on vacant industrial parcels could produce substantial new revenue. A 50 MW facility on a formerly vacant Philadelphia parcel could generate an estimated $5–15 million annually in combined local revenue. Across roughly 170 million square feet of vacant industrial space in the ten largest cities, the aggregate opportunity reaches into the hundreds of millions annually.
V. First-Mover Advantage
Jurisdictions that pre-zone vacant industrial corridors, expedite utility interconnection, and offer fiscally responsible incentive frameworks will pull investment from slower competitors. The resulting tax revenue—property taxes on high-value equipment, sales taxes on refresh cycles, utility taxes on massive electricity consumption, and payroll taxes—represents new revenue that does not burden existing residents. Unlike rate increases on constituents, data center revenue flows from corporate capital entering previously unproductive parcels. For cities facing tightening budgets, this is the rare opportunity that expands the tax base without raising taxes on existing taxpayers.
Conclusion
Policymakers should act on three fronts: streamline rezoning through adaptive-reuse overlay districts; condition remaining incentives on job creation, water-efficiency, and grid co-investment commitments—as Virginia's new 1.1¢/kWh electricity tax begins to do; and require annual, project-level disclosure of forgone subsidy revenue. The convergence of record industrial vacancy, acute power scarcity, and a national reckoning over billion-dollar tax giveaways creates a once-in-a-generation opportunity to convert idle urban infrastructure into productive, revenue-generating digital assets.